Borrow Smarter
Before You Refinance for Any Reason or Take Cash Out of Your Home, Know the Math.
So you don't make a costly mistake you can't take back.
There are many reasons to refinance or take cash out of your home, and many wrong ways to do it. A new loan can pay off your credit cards in one day. But if you don't know this one thing, the cards often fill back up. None of it matters if you don't Know Your Numbers. Borrow Smarter shows you how to Know Your Leftover Number, direct your money instead of your money directing you, and then Know the Math to pick the loan that fits the job, putting the safety and certainty of a fixed rate first.
New course coming by January 2027.
Join the waiting list and get in 48 hours before everyone else.
Wherever you live, this is for you. The education works the same in every state. If a rule changes by state, I'll show you how to check yours.
A New Loan Can Pay Off Your Cards in One Day. Here's How to Keep Them Paid Off.
A lot of people refinance or take cash out to wipe out their credit cards. The cards go to zero. It feels great. But for too many people, a year or two later, the cards are full again. Now the old debt is inside your house, and the new debt is back on the cards.
Here's the hard part to hear. Unless something unplanned happened, like a job loss or medical bills, credit card debt is usually a sign of one thing: not knowing your numbers.
Too many people rush into big money decisions with their home. Most never learn the math. Most don't know their starting numbers. And if you don't know where you're starting from, how can you know if, or when, you'll ever get where you want to go?
That one thing is your Leftover Number: how much money is really left at the end of each month. It's your starting number. And most people have no idea what theirs is.
Most people hate the word "budget." So I don't use one. I teach The Leftover Method: a simple way to decide where your money goes, instead of your money deciding for you. Same result. No budget.
5 Costly Mistakes People Make When They Refinance or Take Cash Out.
Most people don't find out until after they sign. You can find out now.
Looking only at the monthly payment.
A lower payment can still cost you thousands more over the life of the loan.
Stretching 5-year debt into a 30-year loan.
Your cards get paid off today. Then you keep paying for them for 30 years.
Trading a fixed rate for one that can go up.
Your payment can rise when you can least afford it.
Paying points and fees that take years to earn back.
Many people move or refinance again before they ever break even.
Paying off the cards without fixing what filled them up.
The cards fill back up, and the old debt is still inside your house.
Borrow Smarter shows you how to avoid all 5, before you sign. Save my spot
What would it feel like to have your cards paid off, and know you made the safest choice?
- One payment instead of 5.
- More money left at the end of every month.
- No balance that keeps growing while you sleep.
- Your cards stay at zero, because you're the one directing your money now.
- You made the choice with the math, not a sales pitch.
- You're one step closer to retiring with no house payment.
What You'll Learn in Borrow Smarter.
- Your Leftover Number: how much is really left at the end of each month.
- The Leftover Method: how to direct where your money goes, without a "budget."
- Why credit cards fill back up after a refinance, and how to keep them at zero.
- The true cost of a loan, beyond the monthly payment.
- Why a fixed low rate should be the last debt you pay off, and the risk of trading it for a rate that can change.
- Already have a low rate? When keeping it and adding a fixed 2nd mortgage can beat a refinance.
- Cash-out refinance, HELOC and fixed 2nd mortgage, side by side.
- How points and closing costs change the math.
- When a refinance really saves you money, and when it doesn't.
- What to avoid: stretching 5-year debt into a 30-year loan.
Know Your Numbers. Know the Math. Results vary. Financial education, not financial, legal, or tax advice.
Is This for You?
This is for you if...
You own a home, and you're thinking about a refinance, taking cash out, a HELOC, a 2nd mortgage, or paying off debt. Debt from a job loss, medical bills or another surprise? This is for you too. The math works the same.
Not for you if...
You don't own a home yet. That's Qualify Smarter. Close to retiring and want the house payment gone? That's Retire Smarter.
Why People Trust Gregg With the Math.
Since 1998, I've done more than 1,500 mortgages, mostly refinances. Hundreds of my clients have refinanced with me 4 or more times, most never paying closing costs. Together, we've saved over $3.5 million in closing costs.
"I highly value Gregg's advice because his mortgage expertise has directly strengthened my family's financial security over the last decade. He is remarkably knowledgeable, responsive, and professional."
Steve M., Investigator
"I know that he wants to make sure I am in the best financial circumstances I can be in, with respect to a mortgage, regardless of whether those circumstances are necessarily profitable for him."
Scott H., Deputy Attorney General
"Gregg helped me refinance 3x's in a very short period of time & I was able to keep my home. As time went on I had other mortgage decisions come up & Gregg has ALWAYS been reliable."
Serene P., Retired, City of Huntington Beach
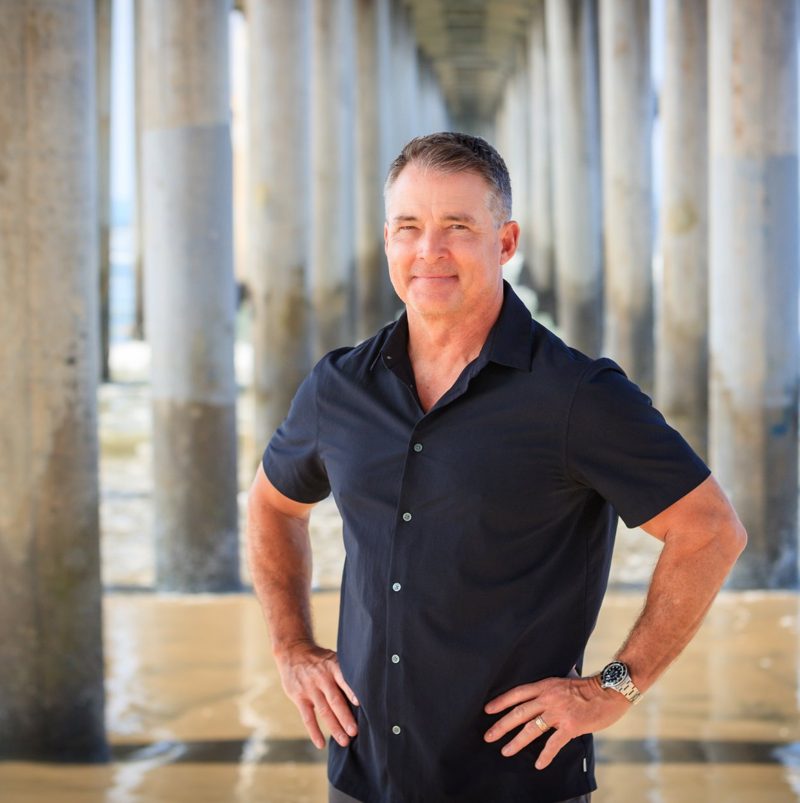
Serve to Protect.
I'm Gregg Knight. I've been a mortgage pro since 1998. I bought my first home at 28 and paid about $3,800 in points I didn't need to pay, because no one showed me the math. I've spent my career making sure you know the math before you sign.
Protecting people was my first career, as a police officer. Now I do it by teaching the math before you make a decision you can't undo.
Questions People Ask.
Is this only for California?
No. Wherever you live, this is for you. The education works the same in every state. If a rule changes by state, I'll show you how to check yours.
Do I have to refinance?
No. Sometimes the smartest loan is no new loan at all. The math shows you which.
Is a HELOC or a 2nd mortgage bad?
No. Each one is a tool. But a HELOC's rate can change. Trading a fixed low rate for one that can go up adds risk to your home. The math shows you when a tool fits your goal, and when it doesn't.
Is this a sales pitch for a loan?
No. It's a course. You'll learn the math so you can judge any loan offer yourself, from any lender.
When does it open?
By January 2027. Join the waiting list and you'll be the first to know.
Save Your Spot.
Borrow Smarter is coming by January 2027. Join the waiting list and get in 48 hours before everyone else.
P.S. The next time a refinance or cash-out offer shows up in your mailbox, you'll want to Know the Math first. Joining the waiting list is free.